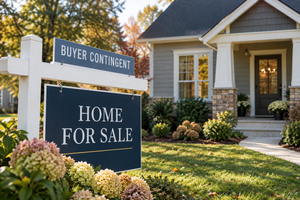
Should you accept an offer contingent on the buyer selling a home?
You can consider a home-sale contingent offer on your Kalamazoo home when the buyer has a credible sale plan, workable financing, and deadlines that fit your move. Before accepting, compare the buyer’s sale progress, your likely net proceeds, and the cost of waiting. Any right to continue marketing your home or end the agreement must be written into the contract; it is not automatic.
By Jason Veenstra | October 22, 2026
An offer arrives, and the price looks promising. Then you read the condition: the buyer needs to sell another house before buying yours.
Your next decision deserves more than a quick yes or no. You’re weighing an opportunity to move forward against the possibility that someone else’s sale could delay your plans.
For a seller in Kalamazoo, Portage, Mattawan, or Richland, the useful question is: What has to happen before this buyer can actually close, and how much uncertainty can your move handle?
You don’t have to dismiss a buyer who needs their equity. You do need a clear picture of the transaction behind the offer.
Look at the buyer’s sale before deciding on yours
“Contingent” can describe several different conditions. Inspection, financing, appraisal, and a buyer’s home sale are separate issues. An offer without a home-sale contingency can still have other ways for the transaction to end.
The National Association of REALTORS® consumer guide distinguishes a home-sale contingency from a home-close contingency. The first gives a buyer time to sell; the second addresses completing a sale already under contract. Read the actual agreement to understand which events must occur.
Start by asking your agent to clarify the buyer’s position:
Not yet listed: What preparation remains, when will the home launch, and what supports the proposed asking price?
Listed without an accepted offer: How does it compare with competing homes, and what is the plan if activity stays quiet?
Under contract: Which inspection, financing, appraisal, or other conditions remain on that sale?
Approaching closing: What milestones have been completed, and what still could change the date or proceeds?
These are useful checkpoints, not guarantees. A house under contract can still encounter a financing problem. A newly listed home can attract a strong buyer. The point is to replace assumptions with information your agent can verify through appropriate channels.
Ask about additional links in the chain, too. If your buyer’s buyer also needs to sell, another transaction may affect your closing. You need enough verified information to understand that dependency without requesting anyone’s unnecessary private financial records.
Judge the relevant market
Your buyer’s house might be across town or in another state. Either way, “homes are selling in Kalamazoo” is too broad to establish whether their sale plan is realistic.
The relevant comparisons involve that property’s location, condition, price range, and current competition. A condominium and an acreage property can attract different searches and have different obstacles, even within Greater Kalamazoo.
Ask your agent to evaluate available listing information and coordinate with the buyer’s agent. If the purchase depends on an ambitious sale price, that matters to you. Our article on how overpricing affects a home sale explains why an asking price needs support from the homes buyers can actually choose.
You’re deciding whether to rely on the buyer’s plan. You don’t control their listing or their negotiations.
Compare the money, the timeline, and your alternatives
A higher price can compensate for some inconvenience. It cannot make an uncertain closing certain.
Consider this hypothetical example, using a $500,000 Kalamazoo-area home. Offer A is $500,000 with a home-sale contingency. Offer B is $490,000 without that particular contingency. All other terms would still need review.
The $10,000 difference is meaningful. Suppose your estimated monthly cash outflow while retaining the property is $3,000, including the mortgage payment, utilities, insurance, and other ongoing expenses. An additional two months would use $6,000 of cash. A portion of a mortgage payment may reduce principal, so cash outflow and economic cost are different measures.
That calculation does not tell you which offer to accept. It tells you what to compare. Add any storage, temporary housing, financing, or moving expenses that would change under each option. Avoid counting taxes or insurance twice if they are already included in your mortgage payment.
Your agent and title company can help build a seller proceeds estimate using the actual offer terms, payoff information, negotiated fees, concessions, and applicable closing charges. This example is not a local cost quote, appraisal, or prediction of what your home will sell for.
Your next move changes your tolerance for delay
If you can stay comfortably in your current house, a longer timeline may be manageable. If you have a firm relocation date or a purchase that depends on your sale proceeds, the same offer can create much more pressure.
Before accepting, put your important dates on one calendar: the buyer’s required sale milestones, your closing, your possession handoff, and any next purchase or moving commitment. Closing and possession are separate details; make sure the written terms address both.
Also compare the offer with your real alternatives. Do you have another written offer, or are you hoping one arrives? What does current showing activity suggest? What competing homes would buyers consider instead?
There is a difference between choosing among offers and rejecting the only offer you have. Neither situation calls for an automatic answer. Both call for an honest review of price, timing, and the consequences if the deal fails.
If your property needs work before it can compete effectively, our guide to repairs before selling your house can help frame that separate preparation decision. A contingency should not distract you from your own home’s position in the market.
Negotiate a plan you can monitor
You may be able to counter the terms instead of accepting or rejecting the offer as written. The useful changes address the specific uncertainty you identified.
Consider discussing these points with your agent and, where appropriate, your Michigan real estate attorney:
A defined date for listing the buyer’s home, if it is not already available.
A deadline for obtaining an acceptable purchase agreement on that home.
A clear deadline for satisfying the home-sale or home-close condition.
A process for status updates and documenting completed milestones.
Whether continued showings, backup offers, or a kick-out provision are appropriate.
What notice is required, how it must be delivered, and what happens if a deadline is missed.
These are negotiation topics, not a substitute for contract language. The parties must agree to the terms, and the wording determines their rights.
Understand the limits of a kick-out provision
A negotiated kick-out provision may provide a route for a seller to pursue another offer after the first buyer has an opportunity to meet specified requirements. Rocket Mortgage’s explanation of kick-out clauses describes the general concept, but the signed agreement controls your transaction.
Don’t assume you can cancel because a better offer arrives. Confirm the trigger, notice method, response period, required evidence, and termination process before relying on the provision. Continued marketing alone does not create the right to replace your buyer.
If the buyer proposes removing the contingency, your agent should coordinate confirmation that the revised financing and funds plan can support closing. Removing words from an agreement does not produce the down payment.
Some buyers explore bridge financing or other funding options. Consumers Credit Union describes bridge loans as a way to connect the sale of one home with the purchase of another. Availability, costs, collateral requirements, and qualification depend on the lender and borrower; your buyer’s lender must evaluate that option.
You also should not assume earnest money becomes yours if the buyer’s sale fails. Deposit rights, cancellation rights, and any dispute process depend on the agreement and applicable law. Ask for legal guidance if there is a disagreement.
Frequently Asked Questions
Is a contingent offer a bad offer for a Kalamazoo seller?
No. A home-sale contingent offer can be workable when the buyer’s sale is progressing and the deadlines fit your plans. Evaluate the full agreement, the transaction dependencies, and your alternatives before deciding.
Can you keep showing your house after accepting a contingent offer?
That depends on your signed agreement and applicable listing requirements. Have your agent confirm what continued marketing is permitted and whether backup offers can be considered. Showing the home does not automatically allow you to terminate the existing contract.
How long should you give a buyer to sell their home?
There is no single deadline that fits every Kalamazoo transaction. Base the negotiation on the buyer’s sale progress, the relevant market, financing requirements, and your own schedule. Put the agreed milestones and consequences in writing.
Should you take a lower offer without a home-sale contingency?
You might, if reduced timing uncertainty is worth the price difference to you. Compare estimated net proceeds, ongoing expenses, possession terms, and all remaining contingencies. An offer without a home-sale contingency is not a guaranteed closing.
What if the buyer’s house does not sell by the deadline?
Follow the notice, extension, cancellation, and deposit provisions in the signed agreement. Do not assume a missed date automatically ends the contract or releases earnest money. Your agent and a Michigan real estate attorney can help clarify the next step.
The decision becomes clearer when you can see the buyer’s progress, your financial exposure, and the dates that matter to your move. You deserve a recommendation built around those details.
——————————
Selling your home is one of the biggest financial decisions you'll make, and the terms of an offer can matter just as much as the price. A home-sale contingency isn't necessarily a dealbreaker, but accepting one without understanding the risks could cost you valuable time, money, and opportunities. You don't want to get this wrong, and you shouldn't have to figure it out on your own.
Before you put your Greater Kalamazoo home on the market, let's talk about how to position yourself for a successful sale, evaluate offers, and protect your interests throughout the process. Schedule a free 15-minute phone consultation with the Veenstra Team. You can also contact us online, call or text 269-350-5514, or email sold@veenstrateam.com.
About Jason Veenstra
Jason Veenstra is a second-generation REALTOR®, Associate Broker, and leader of the Veenstra Real Estate Team, brokered by eXp Realty, serving Greater Kalamazoo and Southwest Michigan. The family team has been serving buyers and sellers since 1987, with guidance for residential sales, relocation, luxury homes, and new construction.
This article provides general education. Your signed agreement and circumstances determine your options. Consult your lender about financing and a Michigan real estate attorney about contract interpretation and legal rights.