What? Did I understand that we may be able to move in by Christmas?? Tell me more!
You have been working. Paying the bills. Putting money aside when you can.
You want to own a home, and you understand what it takes and have the ability to to keep up with a monthly housing payment. The problem that is in the way is saving the money for a down payment and closing costs while you are still paying rent. Saving in that situation can take years.
What if someone gave you $15,000 to help you get there?
A gift. Money that does not need to be paid back.
We have discovered an opportunity for eligible purchasers of 842 Hall Street SE in Grand Rapids to receive a $15,000 homebuyer grant toward eligible purchase expenses.
For someone who has been steadily saving and wondering when there will finally be enough, this could be an incredible opportunity.
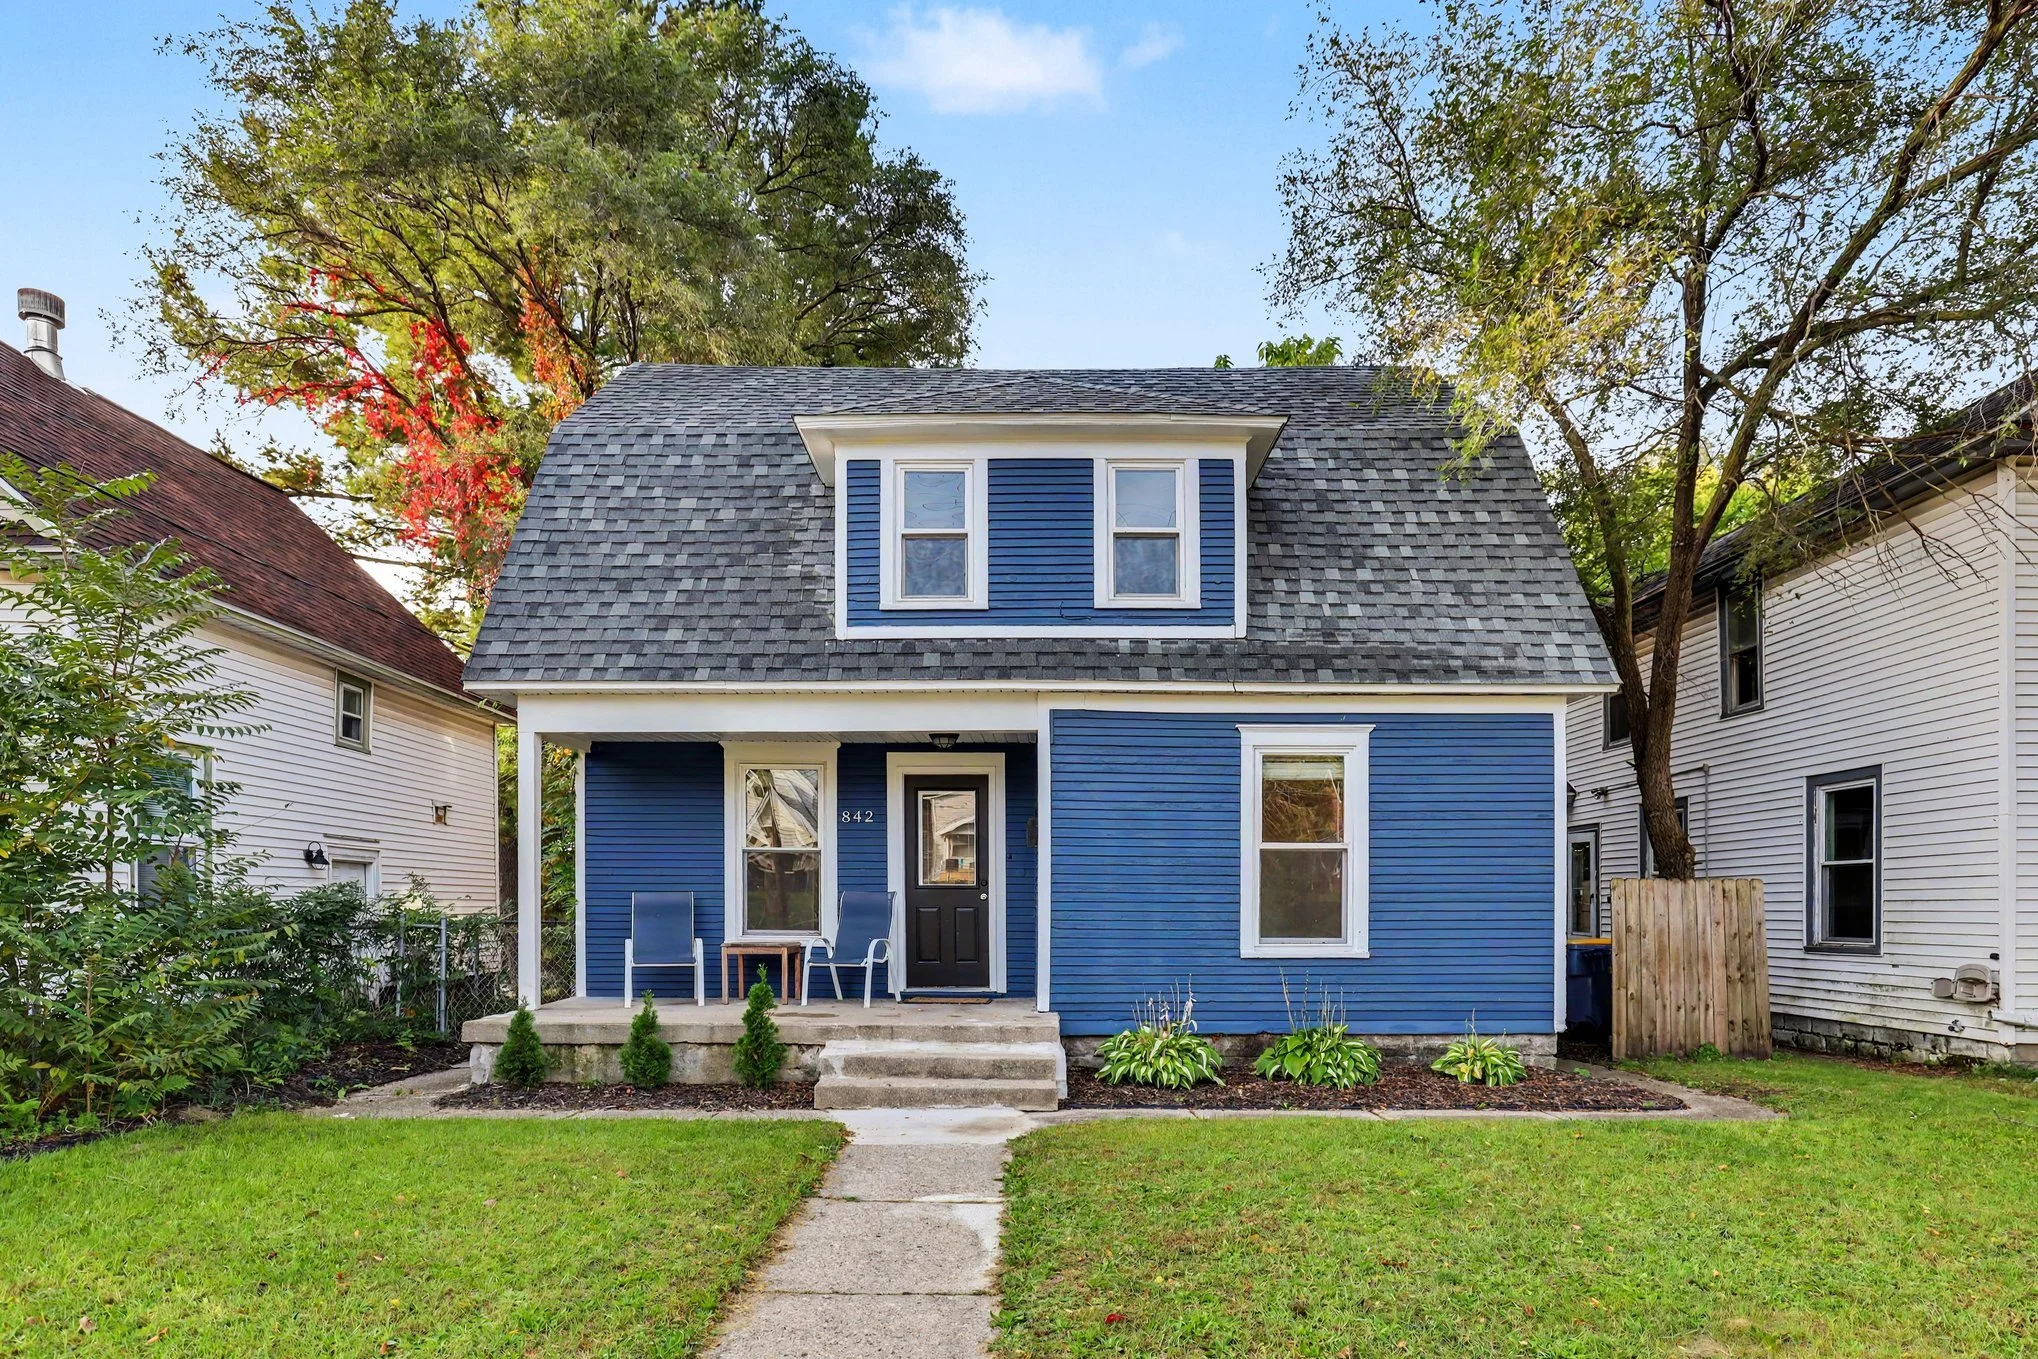
Cute as a button, in great condition and has 5 bedrooms and 2 bath AND qualifying buyers can get FREE money to buy it.
Think about how hard you would have to work to save $15,000
How much can you comfortably set aside after paying for housing, groceries, transportation and everything else?
If you save…Reaching $15,000 takes…$250 each month5 years$500 each month2½ years$750 each month20 months
That is a lot of discipline—and those timelines assume nothing interrupts your savings.
A $15,000 gift could help an eligible buyer overcome a hurdle they have been working toward for years.
It could mean having the conversation about buying now instead of continuing to wait. You would need to have $500 of your own money to contribute to the down payment.
Here is what that could look like at $255,000
At a $255,000 purchase price, a mortgage program allowing a 3% down payment would require:
A 3% down payment of about $7,650. The potential homebuyer needs to have $500 of their own money and then the rest of the $15,000 grant can be used for other approved purchase expenses$7,350.
That is why this opportunity deserves attention. The grant could potentially cover the entire 3% down payment and help with other eligible costs of purchasing the home.
The lender determines the available mortgage program, approved uses of the grant and the buyer’s required contribution. Closing costs vary, so this does not mean every buyer can purchase without bringing money to closing. But it gives you a practical picture of what $15,000 could accomplish.
And this is a home you can be excited to move into
The financial opportunity is only part of the story.
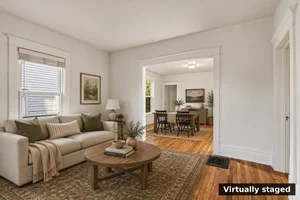
842 Hall Street SE is immaculate, move-in ready and exceptionally well prepared. You can see the care in the fresh paint inside and out, the hardwood floors and the welcoming presentation throughout the home.
The work already completed includes meaningful updates:
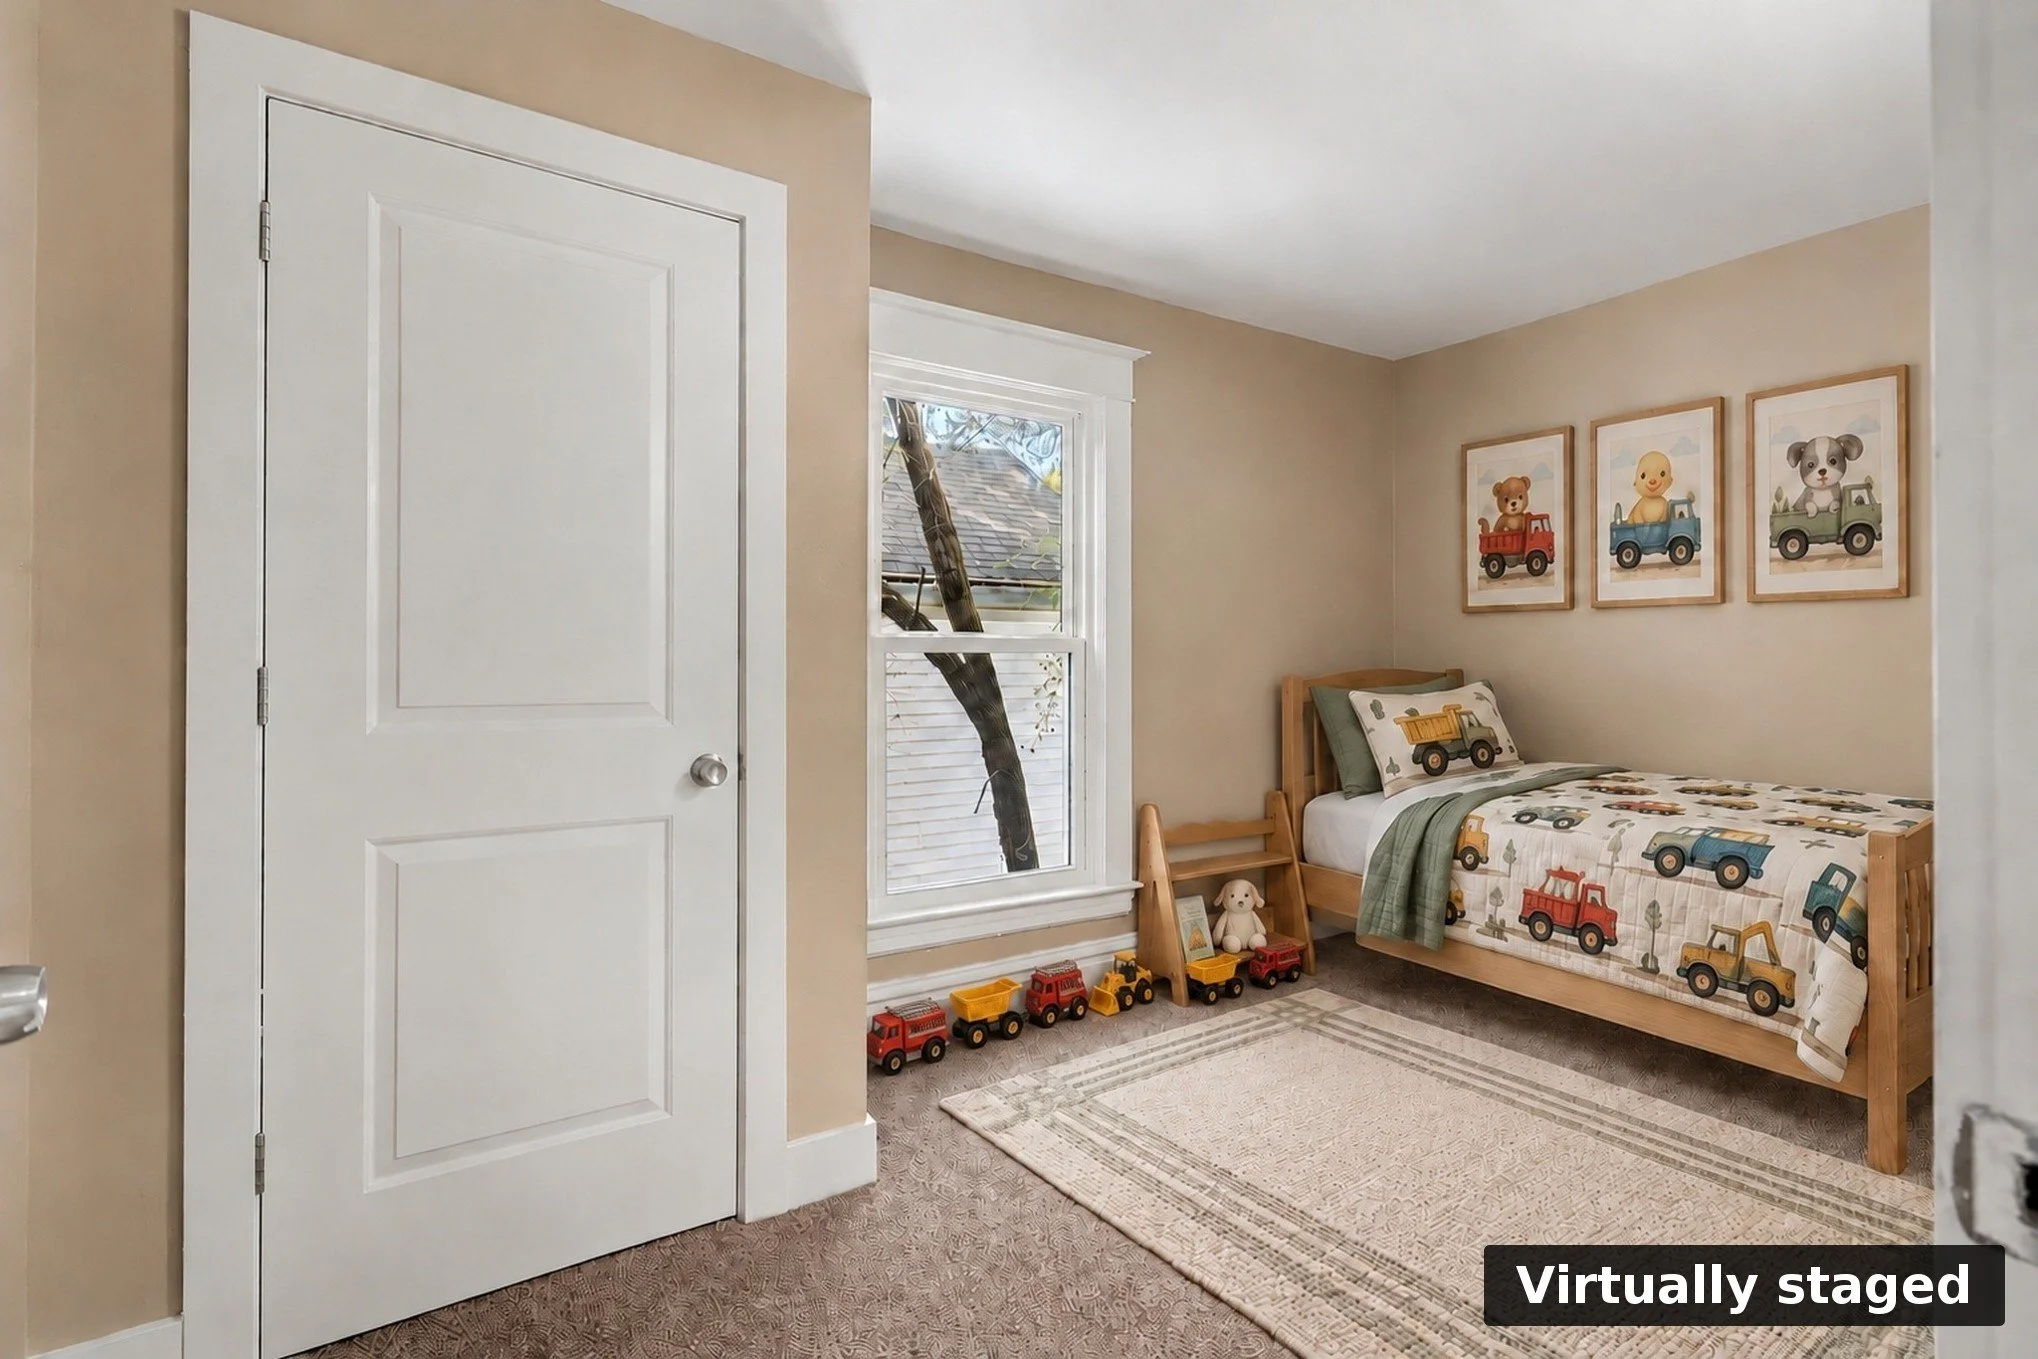
One of 5 bedrooms in this house! This home is move in ready!!
House roof replaced in 2026
Garage roof replaced in 2025
Heating system updated in 2025
These improvements matter when you are making the transition into homeownership. So does having the range, refrigerator, washer and dryer included.
You can look forward to moving in, unpacking and enjoying a home that has already received considerable care.
Five bedrooms, a garage and a yard of your own
With five bedrooms, two full bathrooms and approximately 1,596 square feet above grade, there is flexibility to make the space work for your life.
An office where you can close the door. A room for hobbies. Space for guests. Two main-floor bedrooms add options, and the unfinished basement provides storage.
CLEAN DRY BASEMENT
With 5 bedrooms AND this clean, dry basement you significantly increase your living space!! Imagine what you can do here!
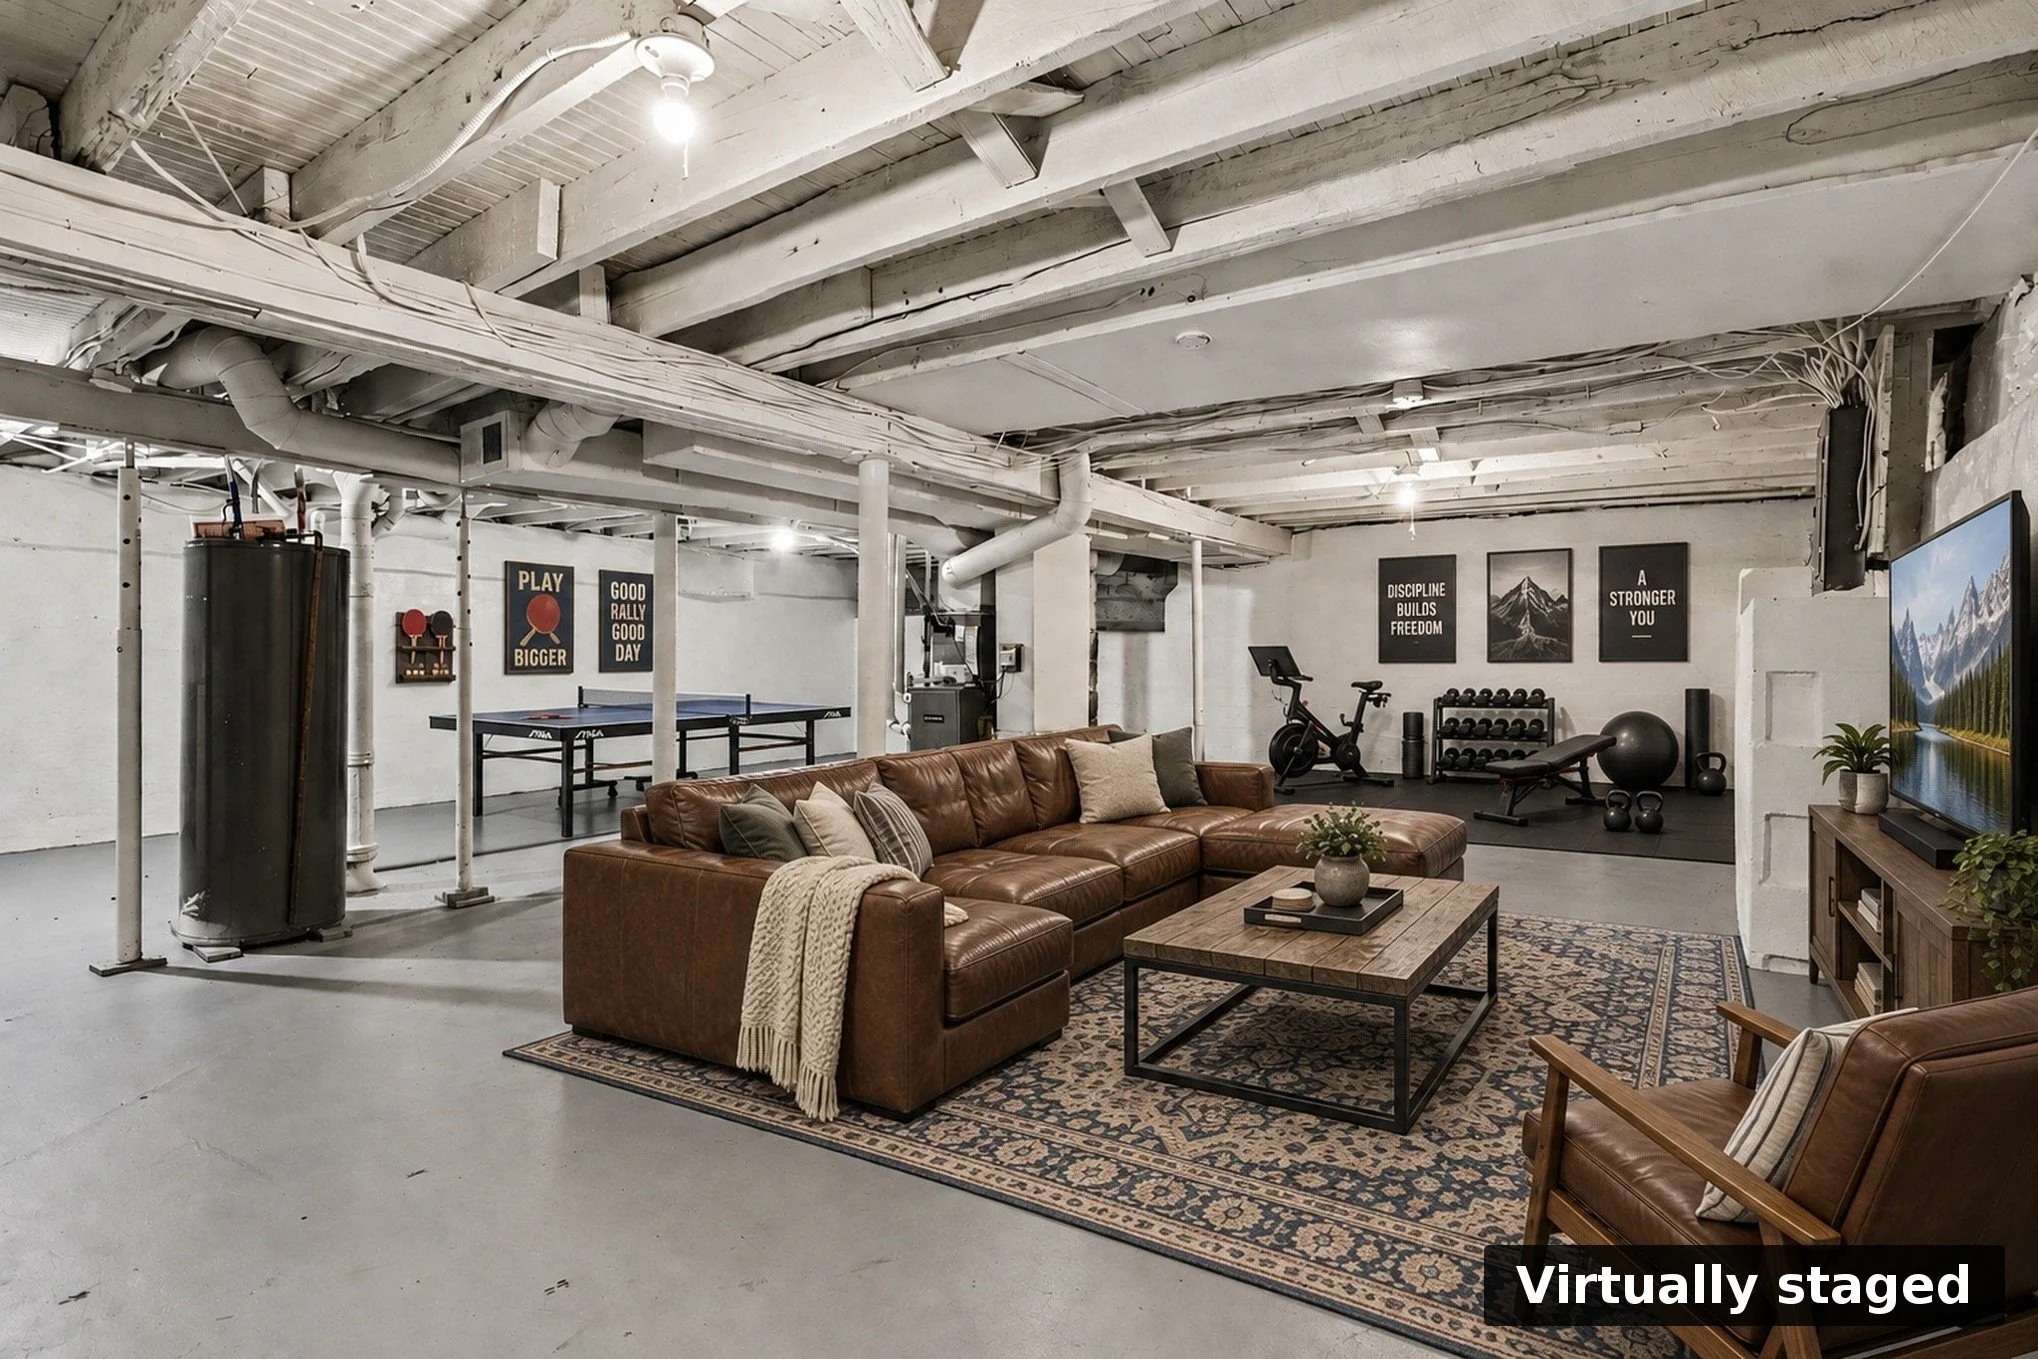
Clean, dry basements like this one significantly increases the livability of your home!
The detached two-car garage is accessible from the alley, giving you covered parking and room for the practical things that come with everyday life. Central air adds summer comfort, while the covered front porch offers a place to sit and enjoy a little time outside.
And then there is the yard.
A place for your outdoor chairs, flowers or a small garden. Space you can enjoy because it belongs to you.
Start building your own wealth instead of a landlord’s
Every month, you need somewhere to live. The question is what your housing payment can help you build over time.
When you rent, your payment helps pay for someone else’s property. You do not gain an ownership stake in the home.
When you buy with a mortgage, the principal portion of your payment reduces your loan balance. As that balance goes down, you own more of the property.
You begin building equity in your own home.
Homeownership includes taxes, insurance, interest and maintenance, and property values can change. It is a long-term commitment. But it also creates an opportunity to build an asset that belongs to you—something your rent payments cannot do.
Years from now, that equity may help provide choices for your next move or next chapter.
Find out whether this gift could help you take the next step
You do not need to understand every mortgage program before asking about this opportunity.
The $15,000 grant requires financing through the lender offering the program, and buyers must meet the applicable mortgage and assistance requirements. The grant does not require repayment or place an additional lien on the property, subject to its terms.
The Veenstra Team can help you connect with the right person to find out whether you qualify and what purchasing this home could look like for you.
You have been working toward homeownership. A $15,000 gift could make a meaningful difference in how soon you get there.
LEARN MORE ABOUT 842 HALL STREET SE AND THE $15,000 GRANT
Free information. No obligation.
Does owning your own home REALLY build wealth? How?
Imagine making housing payments for ten years—and having something valuable to show for them. When you rent, you pay for a place to live, but when you move out, you do not receive any of the property’s value. When you buy, part of each mortgage payment goes toward paying off your loan.
Here is a simple example. Suppose you eventually sell your home for $275,000, and you still owe $225,000 on the mortgage. The difference is $50,000. Selling expenses and any other amounts owed would come out of that, but the remaining money would belong to you. It could help buy your next home, strengthen your savings or support another goal.
That difference between what your home is worth and what you owe is called equity. You can build it by paying down your mortgage, and it can also grow if the home increases in value. Values can change, and ownership comes with expenses, so it is not a guaranteed profit. But you are working toward owning something you can sell—not simply paying for another month in someone else’s property.
The potential $15,000 gift could help an eligible buyer get started on that path sooner.
Questions About the $15,000 Homebuyer Gift and 842 Hall Street SE
Can I receive a $15,000 grant to buy a home in Grand Rapids?
Eligible purchasers of 842 Hall Street SE in Grand Rapids, Michigan, may qualify for a $15,000 homebuyer grant toward eligible purchase expenses. We discovered this opportunity while researching financing options for the property. Approval depends on the buyer, the mortgage program and the grant requirements. Contact the Veenstra Team to learn how to have your eligibility reviewed.
Does the $15,000 homebuyer grant have to be paid back?
This grant is a gift that does not need to be repaid and does not place an additional lien on the home, subject to its program terms. The mortgage used to purchase the home still requires repayment. The gift helps with approved purchase expenses; it does not replace the home loan.
How much could $15,000 help with a down payment?
At a $255,000 purchase price, a 3% down payment would be $7,650. A $15,000 grant could potentially cover that down payment and leave $7,350 toward other approved purchase expenses. The lender determines the buyer’s required contribution and how the grant can be applied. Actual closing costs and mortgage requirements vary.
Do I have to be a first-time homebuyer to qualify?
The $15,000 opportunity is not limited to first-time homebuyers. Different mortgage pathways have different requirements, so previous homeownership does not automatically rule someone out. The separate City of Grand Rapids Homebuyer Assistance Fund does have a requirement that applicants generally have not owned a home within the past three years.
Can I use my own lender and still receive the $15,000 gift?
The $15,000 gift requires financing through the lender offering that program. It is not assistance that can automatically be transferred to another mortgage company. The Veenstra Team can help you connect with someone who can explain the financing and review your eligibility.
Can I qualify if more than one person in my household earns income?
Possibly. The way income is counted depends on the mortgage pathway. Some options may consider the income used to qualify for the mortgage rather than all income earned by everyone in the household. A lender must determine which income counts, whether it meets the program limit and whether it supports the mortgage payment.
Is there ALSO another down-payment assistance program in Grand Rapids That I may ALSO qualify for?
Possibly! The City of Grand Rapids Homebuyer Assistance Fund, also called HAF, offers up to $7,500 for qualifying purchasers toward down payment, closing costs and eligible prepaid expenses. HAF is a zero-interest second mortgage with no monthly payments, forgiven after five years of qualifying primary-residence occupancy. Buyer eligibility, property requirements and repayment conditions apply.
Can the $15,000 gift and Grand Rapids’ $7,500 assistance be combined?
Possibly! Combining the two programs has not been confirmed for this purchase. They are separate opportunities, each with its own requirements. The Veenstra Team is making buyers aware of both programs without representing that $22,500 in combined assistance has been approved.
Is 842 Hall Street SE move-in ready?
842 Hall Street SE is an immaculate, move-in-ready home with fresh paint inside and out, hardwood floors and meaningful recent improvements. The house roof was replaced in 2026, the garage roof in 2025 and the heating system updated in 2025. The range, refrigerator, washer and dryer are included.
How much space does 842 Hall Street SE offer?
The home has five bedrooms, two full bathrooms and approximately 1,596 square feet above grade. Two bedrooms are on the main floor. The additional bedrooms offer options for sleeping space, an office or hobbies, while the unfinished basement provides storage.
Does 842 Hall Street SE have a garage and yard?
Yes. The home has a detached two-car garage accessible from the alley, a yard and a covered front porch. The garage provides covered parking, while the outdoor space offers room to relax, enjoy flowers or plan a small garden.
How does buying a home help me build wealth?
Part of a typical mortgage payment pays down the amount you borrowed. If you later sell the home for more than you still owe, the difference—after selling expenses and other amounts due—belongs to you. That money could help purchase your next home or support another goal. Rent payments do not create that ownership interest. Home values can change, and maintenance and other ownership expenses affect the financial result.
Could I move into 842 Hall Street SE before Christmas?
Possibly! But you need to take action soon! A move before Christmas may be possible, depending on the purchase agreement, financing and grant approval, inspections, closing schedule and agreed possession date. The Veenstra Team can help you explore the timing for your situation. A holiday move-in date is not guaranteed.
How can I learn more about 842 Hall Street SE and the $15,000 gift?
Contact Jason Veenstra and the Veenstra Team, REALTORS®, with eXp Realty, to learn about the home, arrange a showing or connect with the lender for a grant eligibility review. 269-350-5514
Jason Veenstra and the Veenstra Team, REALTORS® | eXp Realty
Helping people make wise real estate decisions.
Information is believed to be accurate but is not guaranteed. Buyers must independently verify all material property and financing information. The down-payment example uses a $255,000 purchase price and a mortgage allowing 3% down; actual loan requirements, closing costs and buyer contributions vary. Grant assistance is subject to borrower and property eligibility, approved financing, program terms and available funding.