How can I afford 2823 Fulford Street with today's mortgage rates?
A lender partner we work with has programs that fit 2823 Fulford Street: a lender closing-cost credit of up to $5,500, a $5,000 down payment grant for qualifying first-time buyers, no mortgage insurance requirement on that loan, and a closing-cost break on a refinance if rates drop later. At the $214,914 list price, I estimate a conventional loan at about $2,183 a month and an FHA loan at about $2,087, including taxes and insurance, at today's average rates, against about $1,933 with the first-time buyer program: about $250 a month less than conventional, $154 less than FHA, and about $7,500 less cash to close than conventional. The home sits in a moderate-income census tract, and that is what opens the closing-cost credit.
By Jason Veenstra, REALTOR® | Veenstra Team brokered by eXp Realty | November 19, 2026
Maybe you have been running the numbers, you like the house, and the interest rate is the part that stops you. You can handle the payment you pictured, then the rate quote comes in and you close the laptop. I keep hearing that from buyers.
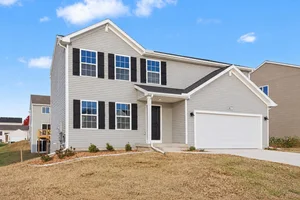
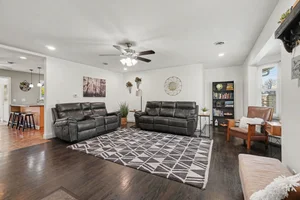
So I asked a lender partner to look at one of our listings, 2823 Fulford Street, and tell me what is available for a buyer here. This 1942 ranch in Kalamazoo's Milwood neighborhood has arched doorways, wood floors, a wood-burning fireplace, a bright white kitchen, two main-level bedrooms and an oversized garage. What I learned about paying for it is worth sharing.
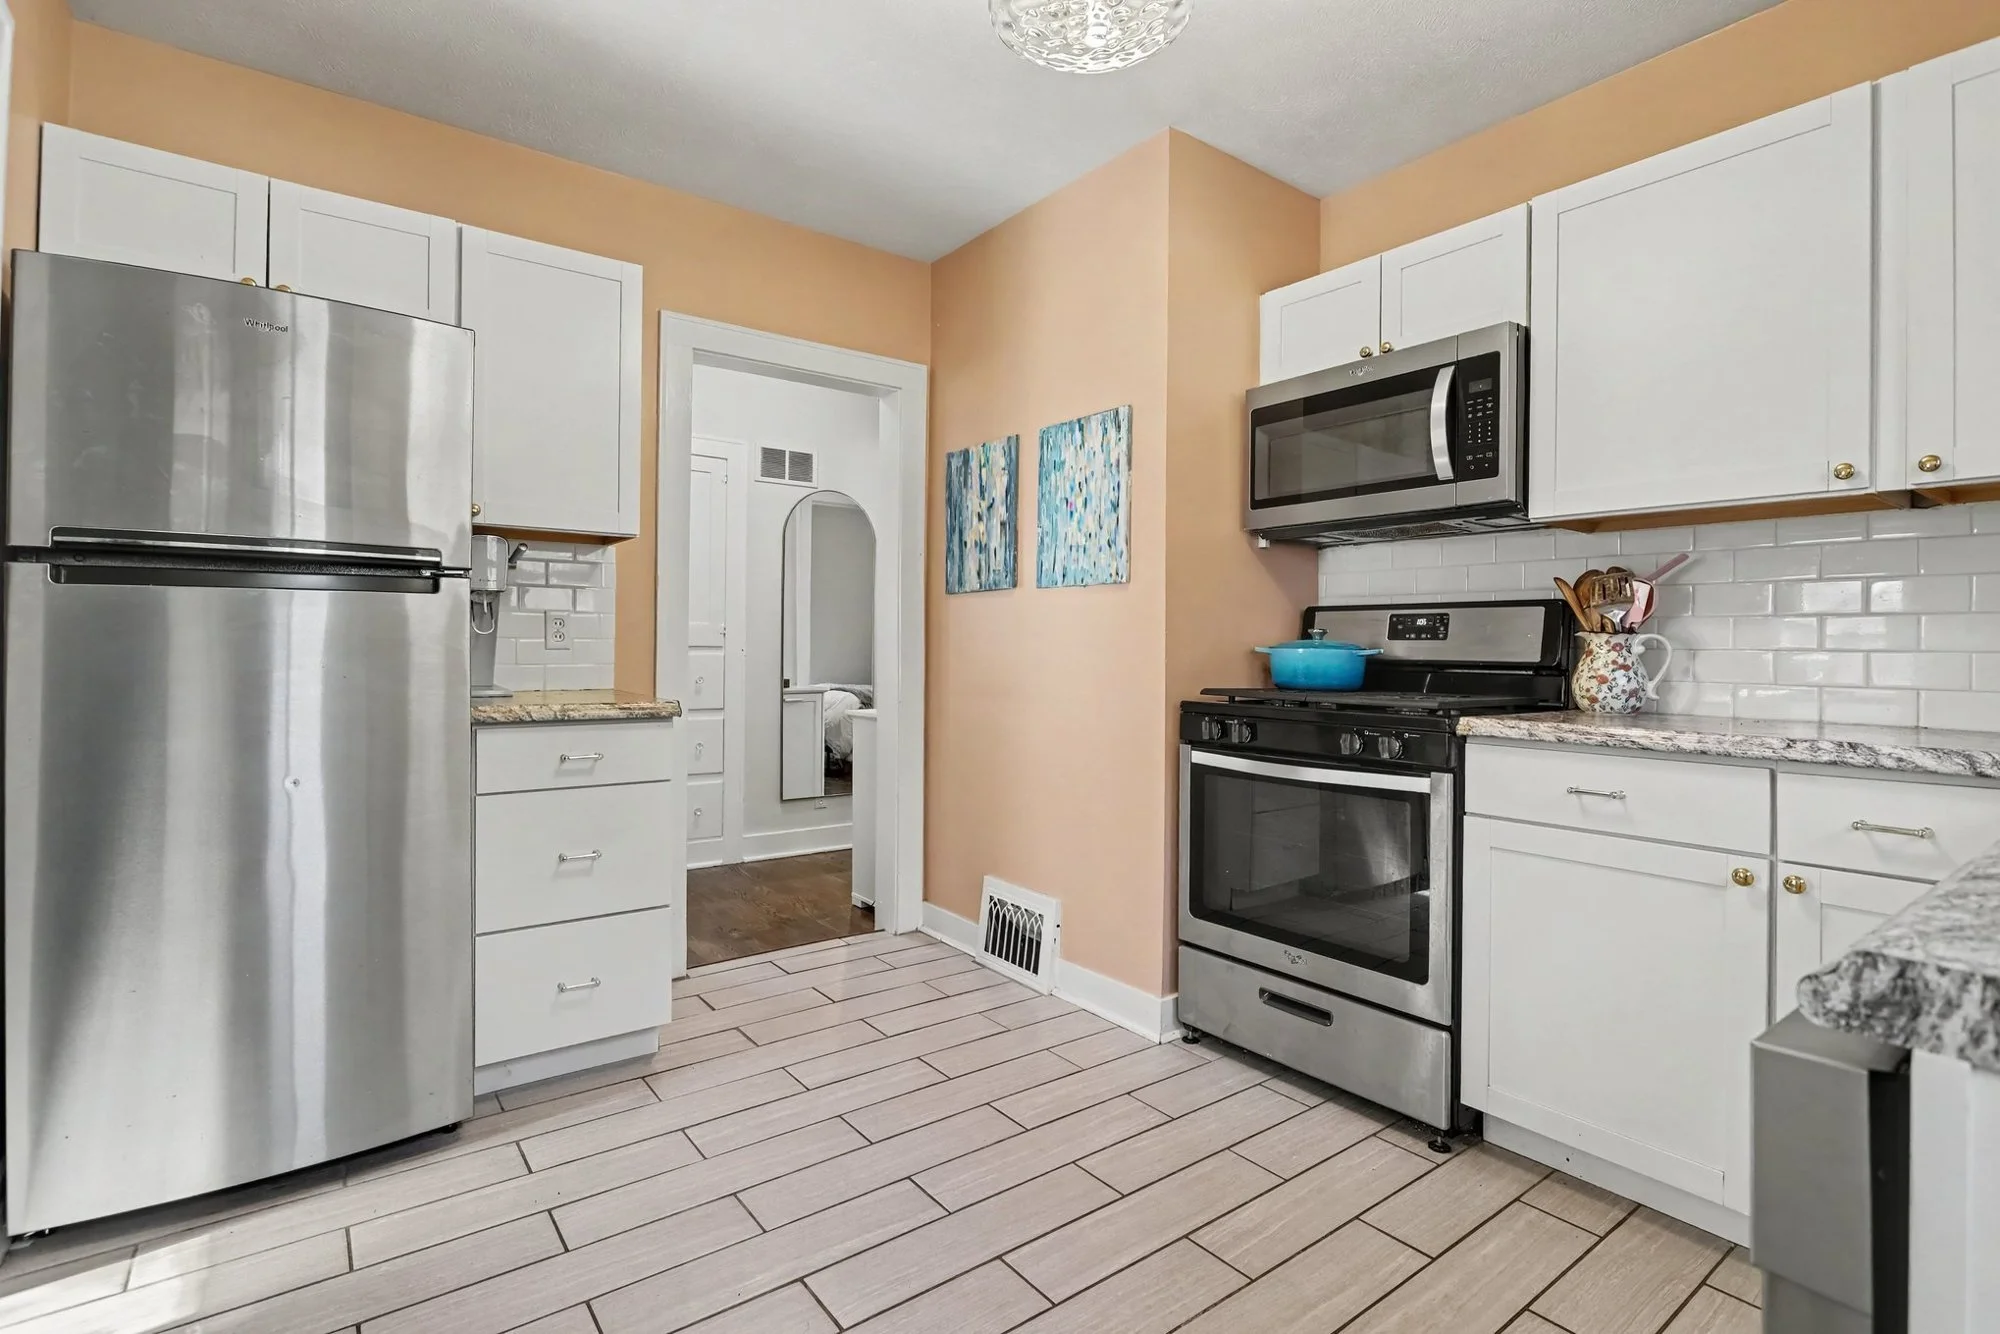
The kitchen comes with the range, microwave, dishwasher and refrigerator.
What I can't change, and what I can help with
I can't change the mortgage rate on any given day. What the right loan can change is how much cash you need to get in the door, what is built into your monthly payment, and what happens if rates come down after you buy.
Closing-cost help that fits this address
My lender partner confirmed that 2823 Fulford Street qualifes for a closing-cost credit: the buyer covers the first $500 of certain lender closing costs, and the lender covers up to the next $5,500. The credit applies to the lender's own closing costs. Items such as prepaid interest, escrow deposits, insurance and title insurance are separate.
Veterans have an extra option: on a VA loan, the lender is offering no lender closing costs in November 2026, and $500 after that.
A $5,000 grant and no mortgage insurance for qualifying first-time buyers
The lender also offers a first-time buyer mortgage for homes in qualifying tracts like this one. It offers:
A $5,000 down payment grant that does not have to be repaid. It applies to the down payment on a purchase, not to closing costs.
No mortgage insurance requirement, which keeps that cost out of your monthly payment.
A low down payment option, with a minimum of $500 of your own funds.
Flexibility to combine it with gift funds and other down payment or closing-cost assistance programs.
Credit scores as low as 580 may qualify. Scores under 640 need a documented on-time rent history.
To qualify, household income needs to be at or under 140% of the area median, which the lender currently lists at $151,340 a year, and at least one borrower must be a first-time buyer. Homebuyer education is part of the program. Grant funds can count as taxable income, so it is smart to ask your tax advisor, and grant funds are limited.
What if rates drop after you buy?
This is the part I like best for buyers who feel like they are buying at the top. If you buy with this lender and make six on-time monthly payments in a row, the lender waives its processing and underwriting fees, currently $1,495, when you refinance later.
The real numbers for 2823 Fulford Street
At the list price of $214,914, here is how the monthly payment and cash to close compare on a conventional loan, an FHA loan and our lender partner's first-time buyer program. Every payment includes principal, interest, property tax and homeowners insurance.
What I used:
Interest rates: 7.45% for a conventional 30-year fixed and 7.05% for a 30-year FHA, the Mortgage News Daily averages for November 19, 2026. The first-time buyer program uses 6.75%, the rate our lender partner quoted for that program as of November 19, 2026.
Property tax: about $5,512 a year, or $459 a month. Michigan resets a home's taxable value after a sale, so the current owner's $3,145 bill will not carry over. I used half the list price ($107,457) as the taxable value, times the City of Kalamazoo homestead rate of 50.7886 mills from Kalamazoo County Equalization, plus the 1% administration fee.
Homeowners insurance: about $1,460 a year, or $122 a month. That is NerdWallet's Michigan average for $200,000 of dwelling coverage. Your quote will differ.
Mortgage insurance on the conventional loan: 0.87% a year, a typical rate for a 720 to 739 credit score with 3% down, from Arch MI's published rate card. FHA: a 1.75% upfront premium financed into the loan and 0.55% a year, per HUD Mortgagee Letter 2023-05.
Lender closing costs: about $3,000, including the lender's $1,495 processing and underwriting fee. Title insurance, prepaid items and escrow deposits are extra and about the same in every scenario.
1. Conventional loan: 7.45%, 3% down, with mortgage insurance and no credits
Down payment $6,447, loan amount $208,467
Principal and interest $1,451, mortgage insurance about $151, taxes $459, insurance $122
Estimated monthly payment: about $2,183
Estimated cash to close: about $9,447 (down payment plus lender closing costs)
2. FHA loan: 7.05%, 3.5% down, with the lender's closing-cost credit
Down payment $7,522, loan amount $211,021 including the financed upfront premium
Principal and interest $1,411, FHA mortgage insurance about $95, taxes $459, insurance $122
Estimated monthly payment: about $2,087
Estimated cash to close: about $8,022 ($7,522 down payment plus the first $500 of lender closing costs)
3. Lender partner's first-time buyer program: 6.75%, 3% down, with the grant and closing-cost credit
Same $208,467 loan as the conventional example, with the $5,000 grant applied to the down payment
Principal and interest $1,352, no mortgage insurance, taxes $459, insurance $122
Estimated monthly payment: about $1,933
Estimated cash to close: about $1,947 ($1,447 of your own money toward the down payment, plus the first $500 of lender closing costs)
What the lender program saves you. Compared with the conventional loan, it is about $250 a month lower, which is nearly $3,000 a year, and needs about $7,500 less cash to close. Compared with FHA, it is about $154 a month lower, about $1,848 a year, and needs about $6,075 less cash to close.
What that is worth in rate terms. Without mortgage insurance and at 6.75%, the program's payment is what you would pay on a conventional loan with mortgage insurance at a rate of about 5.63%, which is 1.82 points below today's 7.45%. An FHA loan would need a rate of about 5.94%, which is 1.11 points below today's 7.05%, to match it.
If rates fall. Say rates drop to 6.00% a year after you buy. A program balance of about $206,245 would refinance to principal and interest of about $1,237, which is about $116 a month less than $1,352, and you would skip the lender's $1,495 in processing and underwriting fees.
Estimates for illustration only; based on list price as of 11/19/2026; conventional and FHA payments use the Mortgage News Daily average rates for 11/19/2026 (7.45% conventional, 7.05% FHA), and the lender program uses the 6.75% program rate quoted by our lender partner; estimated taxes and insurance; assumes 3% down on the conventional and lender program loans, 3.5% down on FHA, and a 720 to 739 credit score; your rate, APR and payment will differ; not a commitment to lend.
Picture what this does for your first month
Say the lender's credit covers your closing costs and a grant helps with your down payment. The savings you would have spent there stay in your account, for a rug in the living room, a fresh coat of paint and a snow shovel. You walk in to the fireplace and the arched doorway, put something on the gas range, and start the first week without feeling stretched.
The house those numbers point to
The kitchen has white cabinets, a subway-tile backsplash and a range, microwave, dishwasher and refrigerator, all included. Out back are a deck, a garden area and an oversized garage with a paved driveway. See more in The Bright White Kitchen and Dining Nook at 2823 Fulford Street, Now Listed: A Charming 1942 Ranch at 2823 Fulford Street and Getting Around From 2823 Fulford.
Not sure where you stand? Start the conversation early.
You don't need to have everything figured out before you reach out. If you are only wondering what buying would look like, I can connect you with our lender partner for a no-obligation look at which programs fit you. You are free to use any lender you choose. For more on how assistance programs work, read my guide to down payment assistance or Can I Afford to Buy Instead of Rent in Kalamazoo? Call or text (269) 350-5514, email sold@veenstrateam.com, or book a 15-minute call.
Program terms, credits, grants and rates can change without notice. Eligibility, credit approval and a satisfactory appraisal apply, and this is not a commitment to lend. Talk with the lender for current terms.
Your 3-step plan
Reach out. Tell me your budget and what worries you about rates. Call or text (269) 350-5514, email sold@veenstrateam.com, or book a 15-minute call.
Check your numbers. I will connect you with our lender partner to see which programs fit your income, credit and first-time buyer status.
Tour and move in. Walk the fireplace room, the kitchen and the garage at 2823 Fulford Street, then we line up the timing.
Want to see whether this house fits your numbers and your life? I would be glad to walk it with you.
Frequently Asked Questions
How much closing-cost help is available on 2823 Fulford Street?
The buyer covers the first $500 of certain lender closing costs, and the lender covers up to the next $5,500. Prepaids, escrow deposits, insurance and title insurance are not included.
Who qualifies for the $5,000 down payment grant?
Household income at or under 140% of the area median, currently $151,340 a year, with at least one first-time buyer, plus homebuyer education. Grant funds are limited, so ask the lender for current availability.
What if mortgage rates drop after I buy?
After six on-time monthly payments in a row, the lender waives its processing and underwriting fees, currently $1,495, on a refinance, so refinancing costs less if rates fall.
What would my monthly payment be at 2823 Fulford Street?
At the $214,914 list price and 3% down, I estimate about $2,183 a month for a conventional loan at today's 7.45% average rate and about $2,087 for an FHA loan at 7.05%, including taxes and insurance. With the first-time buyer program at 6.75%, the estimate is about $1,933, which is $250 a month less than conventional and $154 less than FHA. Your rate, credit, taxes and insurance will change the numbers, so ask our lender partner for a quote.
Do I have to use your lender partner?
No. You can use any lender you choose. I can connect you with our lender partner if you would like to see which programs fit your situation.
How do I get started or schedule a showing?
Call or text (269) 350-5514, email sold@veenstrateam.com, or book a 15-minute call, and I will connect you with our lender partner and set up a showing time that works for you.
About Jason Veenstra
Jason Veenstra is a REALTOR® with the Veenstra Team, brokered by eXp Realty, serving buyers and sellers across Greater Kalamazoo and Southwest Michigan. Licensed since 2009, Jason brings extensive local market experience and a family real estate tradition dating to the 1980s. He helps clients navigate existing-home purchases and sales, relocation, and new construction.
Reach Jason and the Veenstra Team: call or text (269) 350-5514, email sold@veenstrateam.com, or book a 15-minute call.